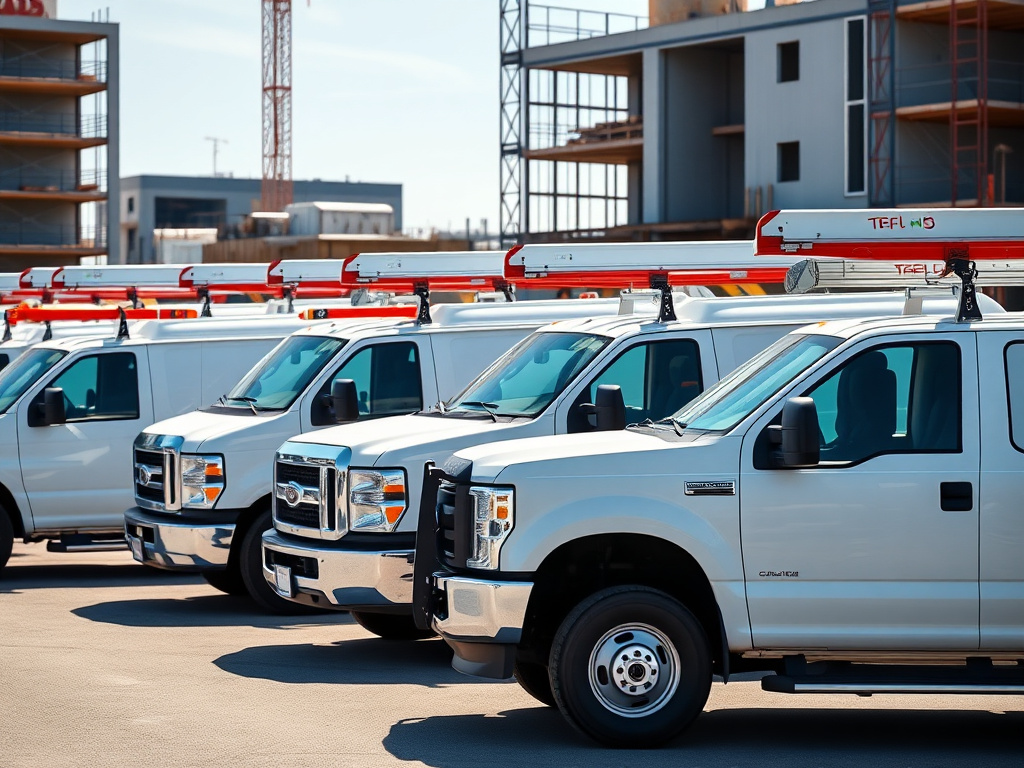
Commercial Auto Insurance for Contractors
Covers the trucks, vans, and fleets that haul your crews and equipment — liability, physical damage, and hired/non-owned auto for the vehicles your business runs on.
Your trucks and vans are rolling toolboxes — they haul your crew, your equipment, and your materials to every job. A personal auto policy won't cover them for business use, which is why contractors need commercial auto insurance. It protects the vehicles your business runs on against liability and physical damage, and it covers the drivers and equipment they carry.
Whether you run a single pickup or a full fleet, commercial auto is a core part of a contractor's program. Buy Contractor Insurance places it alongside your other coverages so your vehicles, your liability, and your equipment in transit are all accounted for — with hired and non-owned auto available for the times your crew drives rented or personal vehicles for work.
Why Personal Auto Isn't Enough
It's a common and costly mistake: a contractor uses a personal pickup for work and assumes their personal auto policy has it covered. It usually doesn't. Personal policies typically exclude or limit business use, which means an accident on the way to a job — or with tools and a crew aboard — can be denied. Commercial auto exists precisely for vehicles used in the course of business, and it's what actually responds when a work vehicle is involved in a loss.
Commercial auto also carries the higher liability limits construction work calls for and can be tied to the additional insured and certificate requirements your contracts impose. For a business whose vehicles are on the road every day, hauling valuable equipment through traffic, that's not a gap you want to discover at claim time.
Coverage That Scales With Your Fleet
One truck or twenty, commercial auto scales to your operation. A single-vehicle policy protects the owner-operator; a fleet policy brings all your vehicles under one coordinated program that's far easier to manage than separate policies. As you add trucks, drivers, and routes, the coverage grows with you.
Because we place your commercial auto alongside your general liability, workers' comp, and equipment coverage, the pieces work together. Hired and non-owned auto fills the gap when a crew member runs to the supply house in their own car; physical damage protects the trucks themselves; and your certificates reflect it all. It's the whole picture, managed in one place.
Who Needs This Coverage
- Contractors using trucks or vans for business — even a single vehicle
- Businesses hauling crews, tools, or materials to jobsites
- Fleets that need one coordinated, scalable policy
- Contractors whose employees drive personal or rented vehicles for work
Commercial Auto Insurance FAQs
More Contractor Coverages
Get Every Contractor Coverage in One Quote
General liability, workers comp, commercial auto, tools, bonds, and more — one place, one quote, built for your trade. Fast turnaround and COIs when you need them.